
The NYC Second-Home Annual Tax: What Owners Need to Know
Last updated October 9, 2026: This is a developing story. On September 29 a judge ordered the city to redo its rollout, the city appealed, and the surcharge is still moving forward. Bookmark this page. I update it as the situation moves.
If you own a New York City property that is not your primary residence, or you are thinking about buying one, this page covers what the new surcharge is, who owes it, what it costs, and what to do if you received a letter from the Department of Finance.

WHERE THINGS STAND RIGHT NOW
The surcharge is being enforced and litigated at the same time, and the situation keeps moving. Here is the sequence.
May 28, 2026: Governor Hochul signed the surcharge into law as part of the state budget for fiscal year 2026-27.
June 5, 2026: The Department of Finance issued proposed rules. A virtual hearing followed on July 9, and the rules were finalized on July 10.
July 1, 2026: The surcharge took effect. It is scheduled to remain in place through June 30, 2031.
July 23, 2026: The city mailed notices to roughly 17,000 property owners and published a supplemental market value roll covering approximately 900,000 properties.
August 1, 2026: The city moved the exemption deadline from August 21 to September 18.
August 7, 2026: Three New York City property owners, represented by former First Deputy Mayor Randy Mastro, sued in Richmond County Supreme Court. Their argument is not that the state lacks power to tax second homes. It is that the city published the roll and mailed notices before determining which properties were actually non-primary residences, shifting onto residents the burden of proving they are not subject to the surcharge.
August 10, 2026: Justice Wayne Ozzi issued a temporary restraining order. It required the city to take the supplemental roll off its website, stop acting on the roll and the mailed notices, and stop enforcing the September 18 exemption deadline.
August 13, 2026: A justice of the Appellate Division, Second Department, stayed the TRO while the city appealed. Implementation resumed.
August 25, 2026: After receiving 2025 state income tax data, the Department of Finance withdrew its determinations for more than 1,200 owners and moved the exemption deadline again, to October 6. It also clarified that appearing on the supplemental roll does not mean a property owes the surcharge.
August 31, 2026: Justice Ozzi heard more than two hours of argument and reserved decision.
September 28, 2026: Former Commerce Secretary Wilbur Ross, Hilary Geary Ross, and Steve Wynn sued the state in Suffolk County Supreme Court. Unlike the Staten Island case, this suit attacks the tax itself. They argue it discriminates against owners who live outside the city and cannot vote against the officials who imposed it, and that it violates the Commerce Clause. A second constitutional challenge on behalf of smaller owners followed the next day. Oral argument in the Ross case is set for November 30.
September 29, 2026: Justice Ozzi ruled for the homeowners. He found the July notices arbitrary and capricious, affected by errors of law, and in violation of due process. His order cancels the roughly 17,000 notices, requires the city to replace the 900,000-property roll with a limited list of properties actually subject to the surcharge, and requires any new notice to explain why the city believes the property owes it. The surcharge itself was not struck down.
September 29, 2026, evening: The city appealed the same night, which automatically stayed the order. The rollout continues while the appeal is pending.
October 5, 2026: The Appellate Division declined the homeowners' request to lift that stay and said it will rule on the dispute by November 10.
October 6, 2026: The city extended the exemption deadline a third time, to October 13. By then it had received roughly 9,300 applications and approved more than 5,200, with roughly 4,000 still under review. Counting earlier corrections, more than 6,400 of the 17,000 flagged properties, nearly 40%, have been found exempt.
October 13, 2026: Current deadline to file an exemption application with the Department of Finance.
By November 10, 2026: Expected Appellate Division ruling on the city's appeal.
November 15, 2026: First surcharge bills are scheduled to go out.
November 30, 2026: Oral argument in the Ross and Wynn case.
January 1, 2027: First surcharge payment due, alongside the January property tax payment.
My read on this (as of October 9, 2026): the September 29 order changes how the city has to run the rollout, not whether the tax exists. Because the appeal keeps that order on hold, nothing has changed for owners yet: the October 13 deadline stands and the first bills are still scheduled for mid-November. The city's own numbers support the judge's concern. More than 6,400 of the roughly 17,000 flagged properties, nearly 40%, have already been found exempt, and more than half of the roughly 9,300 applications filed so far have been approved. If the Appellate Division upholds the order by November 10, I expect the city to send new, narrower notices that explain its reasoning, and bills for some owners could slip past January 1, 2027. If it sides with the city, the rollout continues as it is. Either way, the surcharge itself survives this case. The real threat to the tax is the constitutional suits, the Ross and Wynn case and the second suit on behalf of smaller owners, and I do not expect either to be resolved before the first bills go out, since oral argument in the Ross case is not until November 30. The revenue is also shrinking. The city projected roughly $500 million a year against a projected $5 billion budget gap, and the City Comptroller has said exemptions could bring that down to $340 million to $380 million. With this many exemptions approved, I would not be surprised to see collections at the low end of that range. The city will keep fighting for every dollar of it.
There is also federal noise. President Trump has publicly said the tax must be stopped. As of October 9, 2026, I have not seen that turn into any actual federal mechanism, and I would not plan around it.
The practical takeaway (as of October 9, 2026): if you received a notice and the property is a primary residence, file your exemption application by Tuesday, October 13. Do not wait for the November 10 ruling. The stay keeps the deadline in force, and after three extensions I would not count on a fourth. Use the strongest proof you have, ideally your most recently filed tax return showing the property as your home address. If you miss the deadline, the Department of Finance determination may become final, though you can still go to the Tax Commission by March 1, 2027 for condos and co-ops, or March 15, 2027 for one-, two-, and three-family homes. If the property is a true second home, budget for a bill in mid-November and payment with your January 2027 property tax payment, and make any change in use, qualifying lease or ownership restructuring before January 5, 2027, the next taxable status date. Until a court says otherwise, act as though the tax is fully in force.

THE PART THAT HAS OWNERS ANGRY
The city did not identify non-resident owners by checking residency records. It flagged properties by value, then put the burden on owners to prove they do not owe the tax.
That means full-time New Yorkers who have lived in their apartment for decades are now assembling utility bills, voter registrations, and tax returns to clear their names. If your income tax records do not match the property address in the city's system, or if the records simply did not line up cleanly, you can receive a notice even though the property is genuinely your home.
One detail worth knowing before you submit anything: the Department of Finance has stated that documents you submit to establish primary residence are not protected by the statutory tax-secrecy rules that normally cover tax filings. If you are handing over sensitive financial documents, talk to your attorney about that first.
WHAT THIS TAX ACTUALLY IS
The Second-Home Annual Tax, formally the non-primary residence surcharge, applies to higher-value residential property in New York City that is not being used as a primary residence by the owner, a qualifying family member, or a qualifying tenant.
Two features catch people off guard:
-
It is charged against the property, not the person. It is also separate from your regular property tax bill, though the first payment is due alongside the January 2027 property tax payment.
-
It is not a vacancy tax. Whether the place sits empty is irrelevant. An apartment you use every single weekend is still taxable if it is not your primary residence. A place standing empty for months can still be exempt if it remains someone's primary residence. And it can hit your only New York City home if your primary residence is somewhere else entirely.
The surcharge runs from July 1, 2026 through June 30, 2031.
WHO OWES IT, AND WHO DOES NOT
Property types covered
One-, two-, and three-family homes, condominium units, and cooperative units. Different value thresholds apply depending on type and year.
Property types excluded entirely
These are outside the surcharge regardless of value: vacant land, buildings that have not received a certificate of occupancy, unsold sponsor units still under an active offering plan, and bungalow colonies.
What counts as a primary residence
The property may qualify if it is the primary residence of the owner, of the owner's spouse, child, sibling, parent, grandparent, or grandchild, or of a qualifying tenant.
A person can have only one primary residence for purposes of this tax. If you use more than one home in the city, only one of them can qualify, and the other may be taxable if it meets the value threshold and does not qualify some other way.
You can, however, own several properties in the city without owing on any of them, provided each one genuinely qualifies through a family member or a qualifying tenant.
One correction worth making
You may have seen it said that you are exempt if the property is your primary residence and you pay New York City income taxes. That is not quite right, and the distinction matters. What controls is where you maintain your primary residence, not where you pay income taxes.
Income tax records are how the city screens, which is why the two get conflated. If you file from another state or list a different permanent address on your return, expect to have to establish primary residence through an appeal, even if you genuinely live here.
Rented properties
A property leased to someone who uses it as their primary residence can qualify, provided the lease is genuine, arm's length, and for a term of at least one year. Subleases can qualify if they meet Real Property Law requirements.
For a tenant with a written lease, submit the lease plus one additional rental document. For a month-to-month tenant, the Department of Finance has issued a Tenant or Subtenant Affidavit, which goes in with two additional rental documents.
Be careful here. A lease will not qualify if the circumstances suggest it was created mainly to sidestep the surcharge.
Abatements do not help
Existing property tax abatements, credits, and exemptions do not reduce or offset this surcharge. A condo or co-op abatement may serve as evidence that a unit is a primary residence, but it cannot be applied as a credit, and you still have to prove primary residence separately.
HOW MUCH IT COSTS
The single most important thing to understand: the rate applies to the entire market value, not just the portion above the threshold. This is not how income tax brackets work, and it means crossing a threshold is expensive.

CASE STUDY
Take a condo that sold for $8,400,000 with a current DOF market value of $1,300,000.
Phase 1, years one and two: the DOF value governs. $1,300,000 at 4.0% is $52,000 per year.
Phase 2, years three through five: comparable sales govern. $8,400,000 at 0.8% is $67,200 per year.
Notice what happens. The rate drops sharply, from 4.0% to 0.8%, but the bill goes up, because the valuation basis shifts from the city's assessed value to something much closer to what the property actually sold for. Owners of high-value condos and co-ops with low DOF valuations should model Phase 2 now rather than assume the lower rate means a lower bill.
KEY DATES IN 2027
January 5, 2027: Taxable status date for fiscal year 2027-28. This is the one to plan around. Moving in, signing a qualifying one-year lease, or restructuring entity or trust ownership all have to be done on or before this date to affect next year's liability.
February 15, 2027: Deadline for the Department of Finance to send initial notices for fiscal year 2027-28. That leaves roughly six weeks after January 5 for the city to review records, so make sure your tax return and other proof already match the property address.
March 1, 2027: Tax Commission filing deadline for condo and co-op owners.
March 15, 2027: Tax Commission filing deadline for one-, two-, and three-family homes.
October 1, 2027: If no Tax Commission determination has arrived by this date, contact the Commission with a copy of your application and your date-stamped Form TC10.
October 25, 2027: Deadline to start a court proceeding to review a final Tax Commission determination. This one cannot be extended, and missing it ends your ability to get judicial review.
Why January 5 matters more than anything else
Both the property's value and its primary-residence status are locked in as of January 5 for that fiscal year. Anything you do afterward, moving in, finishing a renovation, signing a lease, generally does not affect the surcharge until a future year.
The city declined to create exceptions for buyers who intended to move in after January 5 or for properties under renovation. There is no proration for part-year changes in use.
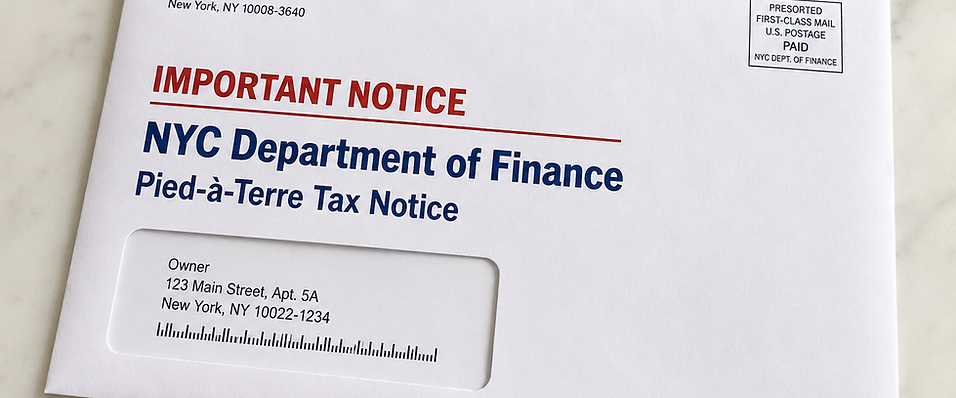
IF YOU RECEIVED A NOTICE FROM DOF
What the notice tells you, and what it does not
It will state the projected surcharge amount and your deadline to appeal. For this first year, it will not explain why the city concluded the property is not your primary residence. You are responding to a conclusion without seeing the reasoning. The September 29 court order would change that by requiring any new notice to explain why the city believes the property owes the surcharge, but that order is on hold while the city appeals.
Notices go to the property address and generally to other owner addresses on file. For co-ops, notice may also go to the unit and to the cooperative corporation.
Do not rely on the mail
Not receiving a notice does not invalidate the surcharge. Check the published list yourself. This matters most for co-op shareholders, because the published list does not include every qualifying co-op unit. The city produced unit-level values for only some cooperative corporations, so units in the remaining buildings simply do not appear. Absence from the list is not a determination that your unit is exempt.
How to prove primary residence
You can generally submit either your most recently filed state or federal personal income tax return showing the property as your permanent home address, or two qualifying documents showing residency on or before January 5.
Qualifying documents include a New York State driver's license, learner's permit, or non-driver ID showing the property address; a voter identification card from the New York City Board of Elections; and other proof the city accepts, including evidence of occupancy during the twelve months before January 5 when paired with one of the listed forms of ID.
The tax return is the strongest proof available and the one most within your control. Because the rules look to the most recently filed return as of the date you appeal, the timing of a filing can matter. Review that with your tax adviser and your attorney before you act on it.
Your appeal routes
These are not interchangeable, and choosing wrong can close doors.
DOF appeal: Filed within 30 days of the initial determination. Addresses primary residence only, not market value. No hearing.
Tax Commission challenge: Can address both market value and primary residence. If you challenge the primary-residence determination here, you must also challenge market value. Deadlines split by tax class, March 1 for condo and co-op, March 15 for one-, two-, and three-family homes.
DOF appeal first, then Tax Commission: Appeal primary residence to DOF, then challenge the final determination at the Commission. Under the Commission's instructions this can be filed by the later of the applicable March deadline or 30 days after the final determination notice. This route preserves both forums. Note that this extension comes from the Commission's instructions rather than the statute, so do not lean on it without counsel.
Market value only: Available at the Tax Commission whether or not you ever appeal primary residence.
The trap: filing a Tax Commission challenge to the initial primary-residence determination shuts down the DOF appeal process and voids any DOF determination already issued. Going the other direction is fine. You can still file at the Commission after finishing a DOF appeal.
If you do nothing, the primary-residence determination generally becomes final, though you keep the right to challenge market value.
Filing mechanics that trip people up
A separate application is required for each property or co-op unit. Joint co-op filings are not allowed.
The application needs an original signature and must be mailed or hand-delivered to the Tax Commission or a DOF Business Center. It cannot be filed by email or fax.
Get Form TC10. It is the date-stamped receipt issued when you file, and it is the only proof of timely filing the Commission accepts. Mailing receipts, certified mail records, and delivery tracking are all rejected as substitutes. TC10 is not the same as TC107, which is the application itself, or TC107SUP, the supplement required when there are multiple owners. Failing to answer TC107SUP results in automatic denial.
An application signed by a representative requires Form TC244 plus a power of attorney. Supporting documentation can generally follow within 30 days of the filing deadline using Form TC159, and extension requests will not be entertained. Supporting documents, but never the application itself, may be emailed to TCSurchargeAppeal@oata.nyc.gov.
The Tax Commission does not hold personal hearings on surcharge review.

OWNERSHIP SITUATIONS THAT NEED EXTRA CARE
Property held in a trust
A trust-owned property can qualify where the people using it as their primary residence are the trust's sole present beneficiaries. Contingent and future interests are not counted in that determination. The city has issued a Trustee Affidavit, sworn by a trustee, for this purpose.
Property owned by an LLC, corporation, or partnership
Entity ownership can qualify, but the requirements are strict. The entity must own the entire interest in the property, or all shares associated with a co-op unit. The people using it as their primary residence, or their qualifying immediate family members, must hold more than 50% of the entity.
For a corporation that means more than half of voting power or stock value. For an LLC or partnership, more than half of capital or profits. Interests can be combined to reach the majority. The city has issued a Majority Interest Affidavit, sworn by an officer of the entity.
Tiered structures generally do not work. You cannot establish primary residence through one LLC that owns another LLC that holds the property. The rules look at your interest in the entity that directly owns the property and do not fully address intermediate entities. If you hold property through a layered structure, this is a conversation to have with counsel now rather than after a notice arrives.
A family member lives there
The property can qualify as the primary residence of a qualifying immediate family member. You will likely need proof that they use it as their primary residence plus proof of the relationship, which can be a birth certificate, a marriage certificate, or affidavits from both of you. The city has issued an Immediate Family Member Affidavit, with the family member completing the top portion and the owner or majority interest holder completing the bottom.
Death, hospitalization, or a care facility
Primary-residence status can continue for one year following the resident's death, during a continuous hospitalization, and during a temporary stay in a nursing or rehabilitation facility. This applies whether the primary resident was the owner, a qualifying family member, or a tenant. Proof of the event and proof of prior primary residence are both required.
Two gaps to be aware of: the rules do not fully define what counts as a temporary stay, and the one-year continuation after a death can run out before an estate is fully administered.
The owner spends part of the year elsewhere
What governs is where you maintain your primary residence, not where you spend the most days or pay income taxes. That said, income tax records drive the city's screening, so filing from another state is a reliable way to end up needing an appeal.
CO-OP OWNERS: READ THIS SECTION
Co-ops are handled differently, and the differences are not in shareholders' favor.
How your value is calculated
A co-op unit has no separately assessed real property value. For Phase 1, the city imputes one by multiplying the cooperative corporation's market value by your unit's proportionate share of total shares.
The resulting figure should appear on the assessment roll and in your notice. But the city has said it will not disclose the share allocation and corporation-level value it used to get there. You receive a number without the math behind it.
One provision that works in your favor
Joint filings are not permitted and each unit needs its own application. However, a market value determination for one co-op unit may be considered when determining values for other units in the same building in the same fiscal year.
This is the only exception to the general rule that determinations set no precedent, and it is worth knowing. A single well-supported application can influence valuations throughout the building. If you are in a building with several affected units, coordinating on one strong filing may be more effective than everyone filing separately and independently.
Collection and lien exposure
The cooperative corporation is responsible for collecting the surcharge tied to an affected unit, and must forward the surcharge notice to the shareholder as soon as practicable.
Any resulting lien attaches at the corporation level, not the unit level. Boards should be reviewing proprietary leases and governing documents now to determine whether they can allocate responsibility to the affected shareholders. If your board has not looked at this, raise it.
BUYING OR SELLING A PROPERTY SUBJECT TO THE TAX
Status is fixed as of January 5. A sale later in the year does not remove the surcharge for that fiscal year and does not get prorated, even if the buyer moves in immediately and makes it their primary home.
Because the charge runs with the property rather than the prior owner, responsibility for any outstanding or current-year liability needs to be addressed in the contract. This is now a standard negotiation point on affected properties, and it is not one to leave to the closing table.
The property can qualify for exemption beginning with the first fiscal year following a January 5 on which it is used as a qualifying primary residence.
If you are buying, ask whether the unit appears on the DOF list and whether a notice has been issued, before you sign.
TOOLS AND RESOURCES
Department of Finance Property Surcharge Eligibility Tool: If you received a mail from the Department of Finance, you can use their following Property Surcharge Eligibility Tool to work out how to reply, including which documents you are likely to need.
Link to the DOS Property Surcharge Eligibility Tool
REBNY's Pied-à-Terre Tax Calculator (Beta): The Real Estate Board of New York has released a calculator to estimate what you might owe.
Link to REBNY's Pied-à-Terre Tax Calculator
QUESTIONS?
If you own a second home in the city, received a notice, or are weighing a purchase and want to understand the exposure before you commit, reach out.
Email:
DISCLAIMER
The information on this page is provided for general informational purposes only and does not constitute legal, tax, or financial advice. Whether the surcharge applies depends on the specific facts of each property, owner, and occupancy arrangement, and the rules are being actively litigated and may change. Owners should consult qualified legal and tax professionals before taking any action.
Frequently Asked Questions
QUESTIONS?
If you own a second home in the city, received a notice, or are weighing a purchase and want to understand the exposure before you commit, reach out.
Email:
Sources: New York City Department of Finance, surcharge final rules adopted July 10, 2026, and deadline announcements through October 6, 2026; New York City Tax Commission, filing instructions and forms TC107, TC107SUP, TC10, TC159, TC244; Real Estate Board of New York, Second-Home Annual Tax FAQ, July 29, 2026; O'Brien v. City of New York, Index No. 85217/2026 (Sup. Ct. Richmond County), including the September 29, 2026 decision, and the Appellate Division, Second Department orders of August 13 and October 5, 2026; Ross Jr. v. State of New York, Index No. 628629/2026 (Sup. Ct. Suffolk County); and contemporaneous reporting on the litigation and the city's exemption figures. Current as of October 9, 2026. This is an active matter and details may change.
DISCLAIMER
The information on this page is provided for general informational purposes only and does not constitute legal, tax, or financial advice. Whether the surcharge applies depends on the specific facts of each property, owner, and occupancy arrangement, and the rules are being actively litigated and may change. Owners should consult qualified legal and tax professionals before taking any action.